
 Team Out of Town
10 Best Credit Cards for Travel in the Philippines: A Comprehensive Guide
If you’re planning a vacation, having the right credit card can make all the difference. From earning miles to getting discounts on travel expenses, the best travel credit cards in the Philippines can help you save money and make your trip more enjoyable. In this article, we’ll introduce you to the 10 best credit cards for travel in the Philippines.

Whether you’re a frequent traveler or just planning a one-time trip, there’s a travel credit card that’s right for you. Some cards offer generous rewards programs that allow you to earn miles for every purchase you make, while others provide discounts on travel expenses like airfare and hotel bookings. With so many options available, it can be difficult to choose the right card for your needs. That’s why we’ve compiled this list of the top 10 travel credit cards in the Philippines.
Before you choose a travel credit card, it’s important to consider your travel habits and spending patterns. Do you travel frequently or only occasionally? Are you looking for a card that offers rewards for everyday purchases or one that provides discounts on travel expenses? You can narrow down your options and choose the right card by answering these questions. So, without further ado, let’s take a look at the 10 best credit cards for travel in the Philippines.
Understanding Travel Credit Cards
These cards are specifically designed to provide rewards and perks to make your travels more enjoyable and affordable. Here are some things you should know about travel credit cards:
Earning Rewards
Most travel credit cards offer rewards in the form of points or miles. You can earn these rewards by using your card to make purchases and redeem them for travel-related expenses such as flights, hotel stays, tour packages, and car rentals.
Sign-Up Bonuses
Many travel credit cards offer sign-up bonuses to new cardholders. These bonuses typically require you to meet a spending threshold within a certain amount of time and can be worth a return flight or a certain number of miles.
Annual Fees
Some travel credit cards come with annual fees. These fees can range from Php1,500 to Php5,000 per year. However, many cards offer enough rewards and perks to offset the annual fee cost.
Foreign Transaction Fees
If you plan to use your travel credit card outside the Philippines, it’s important to be aware of foreign transaction fees. These fees can add up quickly, so looking for a card that doesn’t charge them is a good idea.
Travel Insurance
Many travel credit cards offer travel insurance as a perk. This insurance can cover travel cancellations, lost luggage, and medical emergencies.
Other Perks
In addition to rewards and travel insurance, many travel credit cards offer other perks, such as airport lounge access, free checked bags, priority check-in, priority boarding, and concierge services. These perks can make your travels more comfortable and convenient.
A travel credit card can be an excellent tool for frequent travelers. Just be sure to research and choose a card that fits your needs and budget.
Top 10 Best Travel Credit Cards in the Philippines for 2026
For Filipino travelers, the right credit card can do more than pay for flights and hotels. A good travel card can help you earn airline miles, enjoy airport lounge access, get travel insurance, reduce foreign-exchange costs, and receive rebates on overseas purchases.
Important: Credit-card interest rates, annual fees, foreign-exchange fees, promos, and rewards programs can change. The rates below reflect information available from issuers and their current published materials as of August 2026. If you carry a balance, the interest cost can quickly outweigh travel rewards.
1. BDO American Express Explorer Credit Card

The BDO American Express Explorer Credit Card is one of the strongest choices for Filipino travelers who want to accumulate airline miles through everyday spending. It is particularly attractive for frequent international travelers because it provides unlimited complimentary airport lounge access at participating overseas lounges and up to PHP 10 million in family travel insurance when eligible travel purchases are charged to the card.
The first year’s membership fee is waived, and BDO provides an automatic annual-fee waiver when you spend at least PHP 450,000 per year. The card also supports BDO’s installment programs, including Purchase Convert and Buy Now, Pay Later. American Express cards issued by BDO are accepted worldwide wherever American Express is recognized.
The minimum gross monthly income requirement listed by BDO is PHP 66,000. For regular revolving balances, BDO credit cards generally carry a 3% monthly finance charge, so paying the total amount due every month is important.
Best for: Frequent international travelers who prioritize miles and lounge access.
2. BDO Visa Signature

The BDO Visa Signature stands out because it takes a different approach to travel rewards: instead of relying primarily on airline miles, it gives cardholders a 3% rebate on eligible overseas and airline purchases, plus 0.3% on other purchases, with the travel rebate capped at PHP 2,500 per month. This can be particularly valuable for travelers who spend heavily on airfare, hotels, shopping abroad, and other international expenses.
It also has a relatively attractive 1.70% foreign-exchange conversion rate, up to PHP 20 million in family travel insurance, and two complimentary Priority Pass visits per calendar year. Cardholders can also access the Visa Luxury Hotel Collection and its hotel privileges. BDO lists a minimum gross monthly income requirement of PHP 165,000, making it more suitable for higher-income travelers.
The card also offers lifetime annual-fee waiver eligibility for the principal cardholder after meeting the required annual spend. BDO’s standard credit-card finance charge is generally 3% per month, making full monthly payment essential.
Best for: Affluent travelers who prefer cash rebates over traditional miles.
3. BPI Signature Card

The BPI Signature Card is a premium Visa card designed with international travelers in mind. One of its biggest advantages is its low 1.85% foreign-exchange conversion fee, which can make a meaningful difference when you’re spending heavily overseas.
Cardholders earn 2 BPI Rewards Points for every PHP 20 spent, with points redeemable for airline miles, shopping credits, gift certificates, and other rewards. The card also includes complimentary airport lounge access at selected lounges at NAIA, Visa Worldwide Concierge services, and up to PHP 20 million in travel accident and inconvenience insurance when eligible travel is booked using the card.
The first year is free, while the published annual membership fee from the second year is PHP 5,500. BPI’s current published finance charge is 3% per month, with a 2.73% effective monthly interest rate for applicable regular transactions. The card is particularly compelling for BPI customers who travel frequently and can maximize its points, travel insurance, lounge access, and low foreign-exchange cost.
Best for: Frequent international travelers who want a balanced premium travel card.
4. Metrobank Travel Platinum Visa

The Metrobank Travel Platinum Visa is a popular option for Filipino travelers because it combines airline-mile conversion with premium travel benefits. Metrobank’s rewards program allows points earned on the card to be converted into Philippine Airlines Mabuhay Miles, Singapore Airlines KrisFlyer, and Cathay Pacific Asia Miles.
The published conversion rate for the Travel Platinum Visa is 2.5 rewards points for one airline mile, making it particularly interesting for travelers who are strategic about accumulating miles. The card carries a PHP 5,000 annual fee, waived during the first year, while the first two supplementary cards are free for life. Metrobank currently lists a 3% monthly retail interest rate or 36% annually.
One important consideration is that Metrobank’s standard foreign-exchange and cross-border fees should be checked before international spending because these can affect the effective cost of using the card abroad. For travelers who want flexible airline-mile options rather than being tied to one airline, this card remains one of the strongest mainstream choices.
Best for: Travelers who want flexible access to several major airline loyalty programs.
5. Metrobank Travel Signature Visa
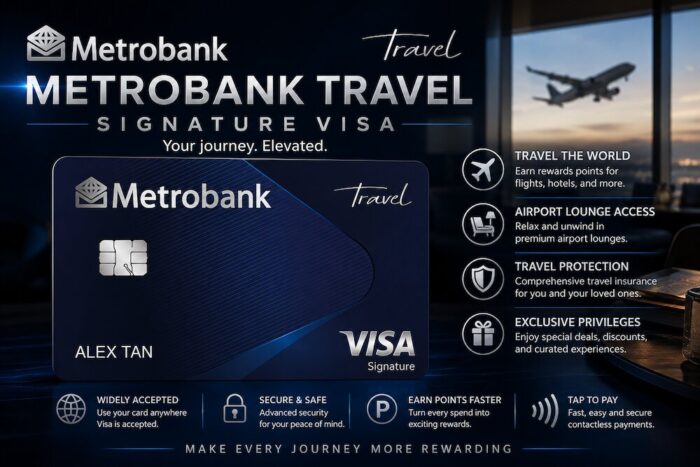
The Metrobank Travel Signature Visa is positioned above the Travel Platinum Visa and is aimed at frequent travelers who spend significantly on their cards. One of its biggest attractions is its airline-mile conversion rate: Metrobank’s current rewards table lists 1.5 rewards points for every airline mile, better than the 2.5-to-1 rate of the Travel Platinum Visa.
Miles can be converted to Mabuhay Miles, KrisFlyer, or Asia Miles, giving travelers several ways to use their accumulated rewards. The card has a PHP 5,500 annual fee, waived during the first year, while the first two supplementary cards are free for life. Metrobank lists the retail finance charge at 3% per month or 36% annually.
The card is best suited to people who regularly charge airfare, accommodation, dining, shopping, and other major expenses to a credit card and pay the balance in full. Its higher annual fee makes less sense for occasional travelers who do not generate enough rewards to offset the cost.
Best for: High-spending frequent flyers who want faster airline-mile accumulation.
6. UnionBank Miles+ Platinum

The UnionBank Miles+ Platinum is an appealing choice for Filipino travelers who want a relatively affordable entry into airline-mile rewards. Its published annual membership fee is PHP 3,000 for the principal card, with a PHP 1,500 supplementary-card fee. UnionBank lists a 2% monthly effective interest rate for this card, which is notably lower than the 3% monthly rate published by many competing Philippine credit cards.
However, cardholders should remember that the lower rate does not make carrying debt inexpensive. The Miles+ program allows users to earn points that can be converted into miles, while UnionBank also supports a range of premium Miles+ products for travelers who want to move up the rewards ladder.
One important 2026 change is that PayDirect transactions no longer earn miles at the previous rate; beginning June 1, 2026, eligible Miles+ PayDirect transactions earn at a reduced rate of one point per PHP150. This makes the card more attractive for genuine travel and everyday spending rather than manufactured rewards strategies.
Best for: Travelers looking for a relatively affordable miles-focused card.
7. RCBC Airmiles Visa Signature

The RCBC Airmiles Visa Signature is one of the most interesting choices for serious Filipino travelers because its rewards are directly designed around airline mileage. Cardholders earn 1 Signature Airmile for every PHP25 spent overseas and 1 Signature Airmile for every PHP48 spent locally.
Even better, Signature Airmiles can be converted at a 1:1 ratio into participating programs including Asia Miles, Mabuhay Miles, and AirAsia Rewards. The card also offers a limited-time 1.50% foreign-exchange conversion fee through December 31, 2026, compared with the standard 1.70%. Travel benefits include complimentary Priority Pass membership with up to four free lounge visits annually, unlimited access to the PAGSS International Lounge at NAIA, and travel insurance coverage of up to PHP20 million.
The annual membership fee is PHP5,500, waived during the first year according to RCBC’s current fee information. RCBC’s standard credit-card interest rate should be checked against its latest fee schedule before application.
Best for: Frequent flyers who want direct, flexible airline-mile conversions.
8. China Bank Destinations World Mastercard

The China Bank Destinations World Mastercard is an excellent option for travelers who want a straightforward points-to-miles system. Cardholders earn 1 Rewards Point for every PHP30 spent, and each Rewards Point is equivalent to one airline mile for participating airline partners. The card also provides up to PHP20 million in travel accident and inconvenience insurance when eligible travel tickets are purchased with the card.
Another major advantage is its 1.7% foreign transaction fee, which is competitive for international spending. Travelers also receive access to Mastercard Travel and Lifestyle Services and a 24/7 Travel and Lifestyle Manager. The card currently comes with a welcome benefit involving a one-year Accor Plus Explorer membership, subject to the bank’s minimum-spend requirement.
Airport lounge access is available through Mastercard Travel Pass powered by DragonPass, although visits may be charged at the applicable rate unless a promotion or qualifying benefit applies. Because rates and fees can change, check China Bank’s latest disclosure for the applicable revolving interest rate before applying.
Best for: Travelers who want simple points-to-airline-mile conversion and a competitive FX fee.
9. EastWest Singapore Airlines KrisFlyer World Mastercard

For travelers who frequently fly with Singapore Airlines or Scoot, the EastWest KrisFlyer World Mastercard is particularly compelling. The card is built specifically around the Singapore Airlines KrisFlyer program. Cardholders earn 1 KrisFlyer Mile for every PHP12 spent on Singapore Airlines, Scoot, KrisShop, travel agencies, hotels, resorts, and cross-border transactions.
Other airlines, local e-commerce, and dining earn 1 mile for every PHP38, while local essential spending earns 1 mile for every PHP78. The card also provides a welcome opportunity to earn 6,000 KrisFlyer miles after PHP200,000 in accumulated retail spending within three months of activation, subject to the applicable terms.
There is also a potential 15,000-mile anniversary offer after PHP200,000 in qualifying spending. The annual fee is PHP5,000, with the first supplementary card free for life. EastWest lists the interest charge at 3% per month or 36% effective annually.
Best for: Singapore Airlines and Scoot loyalists.
10. Security Bank World Mastercard

The Security Bank World Mastercard is a premium travel card worth considering for travelers who value airport lounges and flexible rewards. Cardholders earn 3 BetterBanking Rewards Points for every PHP20 spent, and these non-expiring points can be converted into airline miles and other rewards.
The card comes with six complimentary international airport lounge visits, plus access to local airport lounges, free travel insurance of up to USD100,000, dual-currency billing, and e-commerce purchase protection of up to USD200. The annual fee is currently listed at PHP5,000, with the first year waived. Security Bank’s published credit-card interest rate is 3% per month. The card is aimed at a relatively high-income market, with the bank listing a PHP3 million annual income requirement for the World Mastercard.
Its dual-currency billing can be particularly useful for frequent international travelers because eligible foreign-currency transactions can be billed in USD. For travelers who value lounges and flexible rewards rather than loyalty to one particular airline, it is a strong premium option.
Best for: Affluent frequent travelers who want lounge access and flexible rewards.
Quick Comparison
| Card | Annual Fee | Interest Rate | Key Travel Advantage |
|---|---|---|---|
| BDO Amex Explorer | Based on current BDO schedule; waived with qualifying spend | Generally 3%/month | Miles + unlimited overseas lounge access |
| BDO Visa Signature | Premium fee; waiver possible with qualifying spend | Generally 3%/month | 3% overseas/airline rebate |
| BPI Signature | PHP5,500 after first year | 3%/month | 1.85% FX fee + lounges + insurance |
| Metrobank Travel Platinum Visa | PHP5,000 | 3%/month | Flexible airline-mile conversion |
| Metrobank Travel Signature Visa | PHP5,500 | 3%/month | Faster airline-mile conversion |
| UnionBank Miles+ Platinum | PHP3,000 | 2%/month effective | Affordable miles-focused option |
| RCBC Airmiles Visa Signature | PHP5,500 | Check current RCBC schedule | 1:1 airline-mile conversion |
| China Bank Destinations World | Check current schedule | Check current schedule | 1 point = 1 airline mile |
| EastWest KrisFlyer World | PHP5,000 | 3%/month | Excellent Singapore Airlines earning |
| Security Bank World Mastercard | PHP5,000 | 3%/month | 6 international lounge visits |
Which one should you choose?
Best overall for frequent international travel: RCBC Airmiles Visa Signature
Best for travel rebates: BDO Visa Signature
Best for airline miles: EastWest KrisFlyer World Mastercard or RCBC Airmiles Visa Signature
Best for flexible airline programs: Metrobank Travel Platinum Visa
Best lower-interest option: UnionBank Miles+ Platinum
Best for airport lounges: BDO Amex Explorer or Security Bank World Mastercard
Best for lower foreign-exchange costs: BPI Signature or RCBC Airmiles Visa Signature
One rule matters more than the rewards: pay your credit-card balance in full every month whenever possible. A card earning miles, rebates, or lounge benefits is not a good travel deal if a revolving balance at around 2%–3% monthly interest wipes out the value of those rewards.
Criteria for Choosing a Travel Credit Card
Choosing a travel credit card can be daunting, but it doesn’t have to be. Here are some criteria to consider when selecting the best travel credit card for you:
Rewards Program
The rewards program is one of the most important factors to consider when choosing a travel credit card. Look for a card that offers rewards that align with your travel preferences. Some cards offer points that can be redeemed for flights, hotels, or car rentals, while others provide cashback or discounts on travel-related expenses.
Sign-Up Bonus
Many travel credit cards offer sign-up bonuses that can be a great way to earn rewards quickly. These bonuses usually require you to spend a certain amount within a specified timeframe. Make sure you can meet the spending requirement before applying for the card.
Annual Fee
Most travel credit cards come with an annual fee. Consider whether the rewards and benefits of the card outweigh the cost of the fee. Some cards may waive the yearly fee for the first year, so be sure to check for any introductory offers.
Foreign Transaction Fees
If you plan to use your travel credit card overseas, make sure to check if the card charges foreign transaction fees. These fees can add up quickly and negate any rewards you earn from using the card.
Travel Benefits
Look for a travel credit card that offers additional benefits such as travel insurance, airport lounge access, or concierge services. These perks can make your travel experience more comfortable and enjoyable.
With these criteria in mind, you can select the best travel credit card for your needs and preferences.
Benefits of Travel Credit Cards
Travel credit cards are designed to help you earn more rewards and perks when you travel. Here are some of the benefits of using a travel credit card:
Earn Rewards Points or Miles
Most travel credit cards allow you to earn points or miles for every peso you spend on your purchases. These rewards can be redeemed for flights, hotel stays, car rentals, and other travel-related expenses. Some cards also offer bonus points or miles when you make purchases from specific merchants or when you book your travel through their partner websites.
Enjoy Travel Perks
Many travel credit cards offer exclusive perks such as free airport lounge access, hotel and fuel discounts, and exclusive shopping and dining deals from merchants worldwide. Some cards also offer free travel and accident insurance coverage, which can help you save money on your travel expenses.
No Foreign Transaction Fees
You may be charged a foreign transaction fee when you use your credit card to make purchases in a foreign country. However, many travel credit cards waive this fee, which can save you significant money on your travel expenses.
Fraud Protection
Travel credit cards often come with additional security features, such as fraud protection and zero liability for unauthorized purchases. Knowing that your credit card is protected against fraudulent activity can give you peace of mind when traveling.
Build Your Credit
Using a travel credit card responsibly can help you build your credit score over time. By making your payments on time and keeping your balances low, you can demonstrate to lenders that you are a responsible borrower and improve your creditworthiness.
Travel credit cards can be a great way to earn rewards and save money on your travel expenses. However, it’s important to choose a card that matches your spending habits and travel needs and to use it responsibly to avoid racking up debt.
How to Apply for a Travel Credit Card
The process is quite simple if you’re interested in applying for a travel credit card in the Philippines. Most banks and financial institutions offer online applications, making it easy to apply from home. Here are some steps to follow:
- Research and compare credit cards: Before applying for a travel credit card, it’s important to research and compare the options available. Review each card’s rewards, benefits, fees, and interest rates to determine which best suits your needs.
- Check your eligibility: Each credit card has its own eligibility requirements, such as minimum income, age, and credit score. Make sure you meet the criteria before applying.
- Prepare your documents: When applying for a credit card, you’ll need to provide personal and financial information, such as your name, address, income, and employment details. Make sure you have all the necessary documents, such as your ID, payslips, and bank statements, ready to go.
- Apply online: Once you’ve chosen a credit card and checked your eligibility, you can apply online through the bank or financial institution’s website. Fill out the application form and attach any required documents. Some credit cards may require a minimum spend within a certain period to qualify for sign-up bonuses.
- Wait for approval: After submitting your application, you’ll need to wait for approval from the bank or financial institution. Depending on the card and your creditworthiness, this can take anywhere from a few days to a few weeks.
- Activate your card: Once approved for a travel credit card, you’ll need to activate it before you can start using it. Follow the instructions provided by the bank or financial institution to activate your card, which may involve calling a hotline or visiting a branch.
Following these steps, you can easily apply for a travel credit card in the Philippines and earn rewards and benefits on your next trip.
FAQ: Best Travel Credit Cards in the Philippines
1. What is the best travel credit card in the Philippines?
The best travel credit card depends on how you travel and what benefits you value most. Some cards are designed for earning airline miles or rewards points, while others focus on airport lounge access, travel insurance, hotel privileges, or lower foreign transaction costs. For frequent travelers, cards such as the BDO American Express Explorer, BDO Visa Signature, BPI Signature Card, Metrobank Travel Signature Visa, RCBC Airmiles Visa Signature, Chinabank Destinations World Mastercard, and Security Bank World Mastercard can be worth considering.
2. What should I look for in a travel credit card?
Look at the rewards or miles earning rate, annual fee, foreign transaction fees, airport lounge access, travel insurance, airline and hotel rewards partners, welcome bonuses, and redemption options. It is also important to check the card’s eligibility requirements and whether its benefits match your actual spending habits.
3. Are travel credit cards worth it for Filipino travelers?
They can be, especially for people who travel frequently and pay their credit card bills in full. The rewards, miles, lounge access, travel insurance, and other perks can offset the annual fee. However, occasional travelers should compare the annual fee and actual benefits before applying.
4. Which travel credit cards offer airport lounge access?
Some premium travel credit cards in the Philippines provide airport lounge privileges, although the number of visits, participating lounges, and eligibility conditions vary. Always check the current terms of the specific card because lounge benefits can change.
5. Can I earn airline miles with a Philippine travel credit card?
Yes. Several Philippine credit cards allow cardholders to earn points or miles that can potentially be converted to participating airline frequent-flyer programs. The conversion rate and participating airline partners differ from one card to another, so compare the rewards structure before choosing a card.
6. Do travel credit cards include travel insurance?
Many premium cards offer some form of travel insurance when specific conditions are met, such as purchasing the airline ticket or eligible travel expenses using the card. Coverage, limits, exclusions, and eligibility requirements vary, so read the insurance terms carefully before relying on the benefit.
7. Which travel credit card is best for overseas spending?
A good card for overseas spending should have competitive foreign transaction or currency conversion charges and a rewards program that still provides meaningful value for international purchases. It is also worth checking whether the card offers travel-related promotions, miles, or rewards for foreign transactions.
8. Can I use Philippine travel credit cards abroad?
Yes. Visa and Mastercard cards are generally widely accepted internationally, while American Express acceptance can vary by merchant and destination. Before traveling, make sure your card is active for international transactions and keep a backup payment method.
9. Do travel credit cards have high annual fees?
Premium travel cards often have higher annual fees because they may include benefits such as lounge access, travel insurance, concierge services, and enhanced rewards. However, some banks offer annual-fee waivers or promotions depending on spending and account status.
10. What is the difference between rewards points and airline miles?
Rewards points are usually earned through your credit card’s rewards program and may be redeemed for merchandise, vouchers, statement credits, or transferred to travel partners. Airline miles are generally intended for flights and travel-related redemptions. The better option depends on how frequently you fly and how you prefer to redeem rewards.
11. Can travel credit card points expire?
It depends on the bank and rewards program. Some points have expiration periods, while others remain valid as long as your account meets certain conditions. Check the current rewards program rules before accumulating a large points balance.
12. Is it better to choose a Visa, Mastercard, or American Express travel card?
There is no universal winner. Visa and Mastercard generally offer broad international acceptance, while American Express can provide attractive rewards and travel benefits but may have more limited merchant acceptance in some destinations. Consider where you travel most often and which merchants you typically use.
13. What credit score or income is needed for a travel credit card?
Banks set their own minimum income, credit history, and eligibility requirements. Premium travel cards typically have higher income requirements than entry-level cards. Approval is also subject to the bank’s credit assessment and other application criteria.
14. Should I get a travel credit card if I only travel once or twice a year?
It depends on the card’s annual fee and benefits. If you can recover the cost through rewards, travel insurance, lounge access, or promotional offers, it may still be worthwhile. Otherwise, a regular rewards or cashback card with a lower annual fee may be more practical.
15. How can I maximize travel credit card rewards?
Use the card for eligible everyday purchases, take advantage of bonus categories and bank promotions, redeem points strategically, and pay the balance in full every month. Avoid spending more than you normally would simply to earn rewards, as interest charges can quickly outweigh the value of travel perks.
16. Can I use my travel credit card to book flights and hotels?
Yes. Travel credit cards can generally be used to pay for flights, hotels, tours, and other travel expenses wherever the card network is accepted. Some cards may also provide additional rewards, discounts, or travel protections for eligible bookings.
17. Are travel credit cards suitable for budget travelers?
Yes, but the best card for a budget traveler may not be the most premium card. A card with a reasonable annual fee, useful rewards, low foreign transaction costs, and practical travel benefits can offer better value than a premium card with perks you rarely use.
18. What is the most important factor when choosing a travel credit card?
Focus on overall value rather than the number of advertised perks. Calculate how much you are likely to earn in rewards, how often you will use lounge access or travel insurance, the annual fee, and any foreign transaction costs. The best travel credit card is the one that fits your spending and travel habits—not necessarily the card with the longest list of benefits.
Follow the Out of Town Travel Blog on Facebook, Twitter, Instagram, and Pinterest if you want more travel and food-related updates.
Read: Travel the World with UnionBank Miles+ Visa Platinum Card